Jackson Vandalism Insurance Attorney
Legal counsel for vandalism-related insurance disputes in Jackson
Vandalism can leave a property owner dealing with more than visible damage. Broken doors, damaged locks, graffiti, cut wiring, shattered glass, and tampered systems often create immediate security concerns, but they also raise practical insurance questions. Is the damage covered? Does the policy treat the loss as vandalism, theft, or something else? Has the insurer properly valued the damage? Those questions tend to matter just as much as the repairs themselves.
For homeowners, commercial property owners, and multifamily property managers in Jackson, vandalism claims are not always resolved as cleanly as they should be. Some move forward without much dispute. Others turn on policy wording, documentation, occupancy issues, or disagreements about the cause and extent of the loss.
McWherter Scott & Bobbitt, PLLC, represents policyholders in insurance coverage disputes. The firm advises clients on claim decisions, policy interpretation, valuation issues, and disputes with insurers involving vandalism-related property damage.
Table of contents
- Examples of vandalism that are usually covered by insurance
- How McWherter Scott & Bobbitt evaluates vandalism-related insurance disputes
- First steps after discovering vandalism
- Why vandalism claims get denied or limited
- How vandalism insurance claim disputes are addressed
- Working with counsel on a vandalism insurance claim in Jackson
Examples of vandalism that are usually covered by insurance
Many property insurance policies include some form of coverage for vandalism, though the answer always depends on the policy language and the facts of the loss. In general terms, vandalism involves intentional acts that damage or deface property. That sounds simple enough, but actual claims are often more complex than the label suggests.
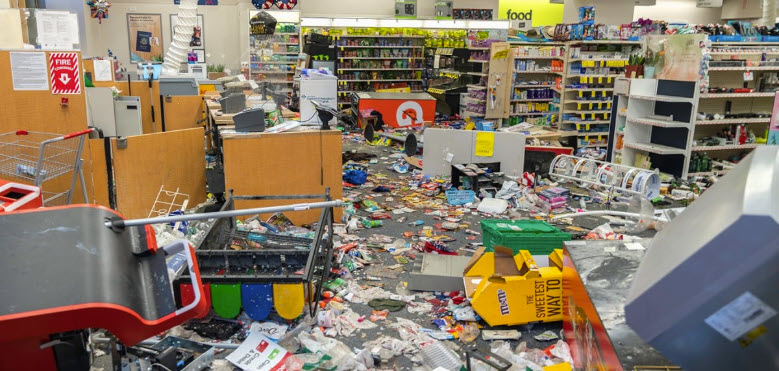
A vandalism claim may involve graffiti on exterior walls, fencing, garages, or entryways. It may involve broken windows, smashed doors, damaged fixtures, or destruction to lighting and other exterior components. In some cases, the damage is more disruptive than dramatic. Locks may be glued shut. Security cameras may be damaged. Gates or access systems may be tampered with. Water lines or other property systems may be intentionally interfered with, creating a broader repair issue than the initial act itself.
There are also situations where vandalism overlaps with theft or attempted theft. A claim file may contain evidence of forced entry, missing items, damaged interior spaces, and damage to surrounding structures. Those losses are not always analyzed the same way. One part of the claim may involve vandalism, while another may involve theft-related policy provisions, limits, or proof requirements.
That distinction matters.
Coverage also depends on the insurance policy and how it applies to the damage. Some policies restrict or exclude vandalism coverage when a property has been vacant for a certain period, though the definition of ‘vacant’ depends on the policy. Others apply deductibles, sublimits, or valuation rules that affect the amount payable even where coverage exists.
In practice, the policy, the condition of the property, and the documentation of the loss usually determine how the claim unfolds.
How McWherter Scott & Bobbitt evaluates vandalism-related insurance disputes
A vandalism claim does not have to be denied to benefit from legal guidance. Even before a clear dispute develops, questions about coverage, proof of loss, scope, and valuation can affect the direction of the claim. Early legal involvement can help policyholders better understand the policy, strengthen the claim record, and reduce the risk that important issues are mishandled.
The attorneys at McWherter Scott & Bobbitt represent policyholders in disputes with insurers. In a vandalism claim, that work may begin with a review of the policy itself, including how vandalism is treated, whether any vacancy-related language applies, what deductibles are involved, and whether the policy uses actual cash value, replacement cost, or another valuation framework. From there, the firm may review the claim investigation, the adjuster’s findings, photographs, repair estimates, and correspondence explaining the insurer’s position.
Sometimes the dispute is straightforward. The insurer denies the claim and gives a stated reason. Other times the problem is less direct. Payment is delayed. Portions of the damage are left out of the estimate. The carrier treats the loss as partly uncovered without clearly explaining why. The insurer may accept that vandalism occurred but assign a value to the repair that does not appear consistent with the scope of the damage or the policy terms.
Those are coverage and claim-handling problems. They call for expert analysis, not slogans.
The firm’s role is to evaluate the insurer’s position, analyze the policy, review the claim record, and challenge denials or underpayment where the policyholder’s claim is not being handled in accordance with the policy terms. Depending on the dispute, that may involve negotiation, appraisals, or litigation.
For a property owner trying to understand whether an insurer has applied the policy correctly, that kind of focused legal review can make the claim process easier to assess.
First steps after discovering vandalism
The period immediately after vandalism is discovered often shapes the claim that follows. The goal is not to create a perfect file overnight. It is to preserve the facts, protect the property, and avoid preventable disputes later.
Start with safety. If the damage affects entry points, electrical systems, water lines, or other essential parts of the property, securing the premises comes first. A home, commercial building, or multifamily property may need temporary measures to prevent additional loss. That could include boarding openings, changing locks, shutting off damaged utilities, or taking other reasonable steps to protect the property from further harm.
As soon as possible, report the incident to law enforcement. A police report is not the only evidence that matters, but it often becomes an important part of the claim file. It creates a contemporaneous record and helps establish that the damage was reported as vandalism rather than discovered much later without explanation.
Documentation should follow as soon thereafter. Photographs and video are useful because they preserve the condition of the property before cleanup, repairs, or removal of debris changes the scene. Wide shots, close-up photos, and images showing how the damage relates to the rest of the property can all matter.
If items were stolen, destroyed, or damaged, a written list can help organize the claim. Ownership records, invoices, maintenance records, prior photos, and receipts may also help support the value and condition of the affected property. That is not always easy, particularly in a business or multifamily setting where the damage touches several different areas or components. Even so, early organization often makes later disputes easier to address.
Temporary repair expenses should also be documented. Reasonable emergency measures are often necessary, but whether the insurer reimburses them depends on the policy and the nature of the work performed. Keeping invoices, receipts, and photographs of the pre-repair condition helps preserve that issue for the claim.
Why vandalism claims get denied or limited
Vandalism claims are often disputed for reasons that have less to do with the visible damage than with how the insurer categorizes and evaluates the loss.
One recurring issue is causation. The insurer may question whether the damage was intentional at all. A broken fixture, damaged fence, or compromised system may be treated as wear, neglect, accidental damage, or deferred maintenance rather than vandalism. If the insurer views the condition differently, the coverage analysis changes with it.
Another issue involves vacancy. Many policyholders are surprised to learn how much turns on whether a property was occupied, unoccupied, or vacant under the policy definition. That language is not always intuitive. A building may appear to be in use from the owner’s perspective yet still trigger a vacancy-related limitation depending on the policy wording and the length of time the condition existed.
Claims may also become more complicated where theft is involved. If property is missing, the insurer may request proof of ownership and, in some cases, evidence of forced entry, depending on the policy terms. Not every vandalism claim includes those issues, but when it does, the theft-related portion of the claim may be adjusted differently from the property-damage portion.
Fraud concerns can also arise. If the insurer believes the loss was staged, exaggerated, or misrepresented, the claim may be denied outright or subjected to a more intensive investigation. Those allegations are serious. They are also highly fact-dependent. Documentation, witness information, police records, photographs, electronic data, and the timing of communications can all become important.
Then there is valuation. Even when the insurer agrees the damage is covered, the carrier may pay less than the policyholder expected because of depreciation, or the policy’s valuation method, such as actual cash value versus replacement cost. In that sense, a claim can be “accepted” and still remain very much in dispute.
How vandalism insurance claim disputes are addressed
Once a vandalism claim becomes contested, the issue is no longer simply what happened to the property. The issue becomes how the policy applies to that loss and whether the insurer’s position is supported by the policy and the claim record.
That is where legal counsel steps in.
McWherter Scott & Bobbitt reviews the claim from the standpoint of coverage and dispute resolution. That usually begins with a close reading of the policy provisions that govern the loss, including covered causes of loss, exclusions, conditions, deductibles, and valuation language. In many claims, the important language is not limited to a single provision. Several policy sections may bear on the outcome.
The firm also reviews the claim investigation itself. That may include adjuster findings, photographs, reservation of rights letters, denial letters, repair estimates, engineering reports, and other materials the insurer relied on in reaching its decision. If contractors, consultants, engineers, or restoration professionals have been involved, their reports may be relevant because they become part of the claim file and may influence how the insurer evaluates the loss.
Sometimes the problem is an outright denial. It could also be a narrower issue, such as an estimate that omits categories of damage, an interpretation of the property condition that does not match the evidence, or a valuation that appears inconsistent with the policy. The legal work depends on the nature of the dispute.
That work can include:
- Analyzing policy provisions relevant to vandalism and related property damage
- Reviewing claim investigations and stated coverage positions
- Evaluating repair estimates, inspections, and expert reports in the claim file
- Challenging denials, partial denials, or underpayment
- Handling negotiations, appraisal, and litigation when necessary
Working with counsel on a vandalism insurance claim in Jackson
Property owners in Jackson do not need broad promises when a vandalism claim turns disputed. They need a clear understanding of what the policy says, how the insurer is handling the claim, and what options exist if the carrier’s position does not appear to match the policy language.
That is especially true where the damage is substantial, the property has unique operational needs, or the loss affects more than one category of property. A vandalism incident at a home raises one set of practical concerns. At a commercial property or multifamily building, the issues may involve security, tenant impact, access control, damaged systems, and questions about how the insurer has separated covered damage from excluded or limited losses. The claim file can become complex quickly.
McWherter Scott & Bobbitt represents policyholders in Jackson and throughout Tennessee in property insurance disputes. The firm’s work is focused on insurance coverage, claim analysis, and disputes with insurers. It is legal counsel directed at policy interpretation and claim resolution.
The office is located at 54 Exeter Road, Suite D, Jackson, TN 38305.
Connect with our lawyers today for a free review of your Jackson vandalism case
Vandalism damage can create immediate repair needs, but the insurance issues often last longer than the visible damage itself. A claim may involve questions about coverage, vacancy conditions, valuation, supporting documentation, or the insurer’s explanation for limiting payment. In some cases, the problem is not whether damage occurred. It is whether the insurer has applied the policy correctly.
McWherter Scott & Bobbitt advises policyholders on vandalism-related insurance disputes in Jackson and across Tennessee. If you have concerns about a denial, a delayed claim, or a payment decision that does not appear consistent with your policy, a careful review of the policy and claim file can help clarify the available next steps.
More Jackson, TN insurance claim types we handle
- Jackson, TN Insurance Dispute Lawyers
- Jackson Tornado Damage Insurance Attorney
- Jackson Water/Mold Damage Insurance Attorney
- Jackson Wildfire Insurance Attorney
- Jackson Wind Damage Insurance Attorney
Reach out today to schedule your free consultation by filling out our form online.